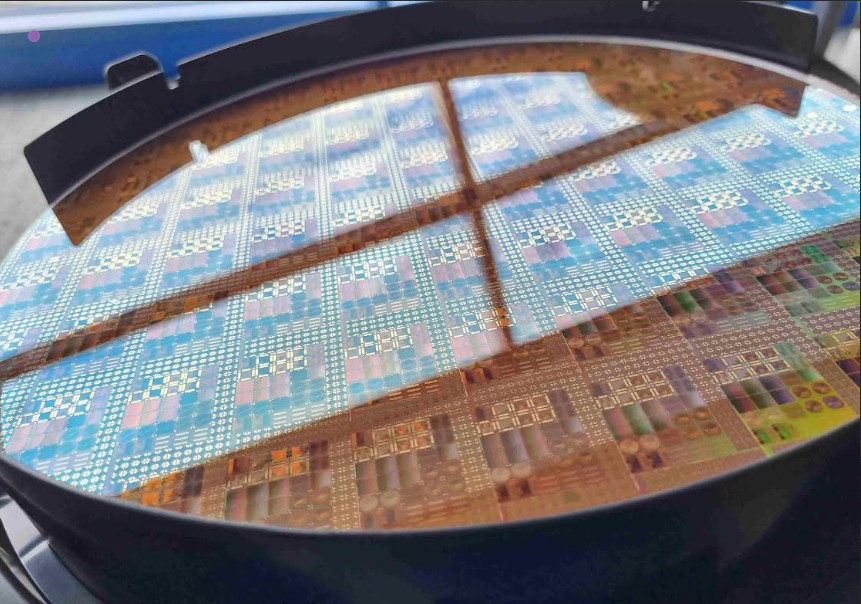

Worldwide semiconductor revenue totaled $476.7 billion in 2018, a 13.4% increase from 2017, according to Gartner, Inc. Memory strengthened its position as the largest semiconductor category, accounting for 34.8% of total semiconductor revenue, up from 31% in 2017.
“The largest semiconductor supplier, Samsung Electronics, increased its lead as the No. 1 vendor due to the booming DRAM market,” said Andrew Norwood, Vice President, Analyst at Gartner. “While 2018 continued to build on the growth established in 2017, the overall gains driven by memory were at half the 2017 growth rate. This is attributed to memory entering a downturn late in 2018.”
The combined revenue of the top 25 semiconductor vendors increased by 16.3% during 2018 and accounted for 79.3% of the market, outperforming the rest of the market, which saw a milder 3.6% revenue increase. This is due to the concentration of the memory vendors in the top-25 ranking.
Intel’s semiconductor revenue grew by 12.2% compared with 2017, driven by a combination of unit and average selling price (ASP) growth. Major memory vendors that performed strongly in 2018 include SK hynix — driven by DRAM, and Microchip Technology — due to its acquisition of Microsemi. The top four vendors in 2017 retained their ranking in 2018.

“The current rankings may see significant change this year with the expectation that memory market conditions will weaken in 2019,” said Mr. Norwood. “Technology product managers must prepare for this limited growth to succeed in the semiconductor industry.”
Memory vendors, for example, will need to plan for future oversupply and intense margin pressure by funding research and development on continued node transitions, emerging memory technologies and new manufacturing technologies. This will provide them the best cost structure as new entrants from China emerge.
Nonmemory vendors must increase design-in activity with key customers that have been enduring high memory pricing. As the market for smartphones and tablets continues to saturate, application processor vendors must seek adjacent opportunities in wearables, Internet of Things (IoT) endpoints and automobiles.
In terms of semiconductor devices, memory was simultaneously the largest (35 percent) and highest-performing device category for 2018 with 27.2% revenue growth. This was driven by increases in ASP for DRAM for much of the year with the exception of the fourth quarter of 2018.
Within the memory segment, NAND flash suffered a marked slowdown with ASP declines through much of the year due to oversupply. This device category still managed to show a 6.5% revenue increase, driven by higher adoption of solid-state drives (SSDs) and increasing content in smartphones.
The second-largest semiconductor category, application-specific-standard products (ASSPs), saw limited growth of 5.1% due to a stalling smartphone market combined with a tablet market that continues to decline. Leading vendors in this segment area, including Qualcomm and MediaTek, are aggressively expanding into adjacent markets with stronger prospects for growth, including automotive and IoT applications.
Merger and acquisition (M&A) activity in 2018 was more significant for the deals that did not happen than the deals that did. Broadcom’s hostile takeover attempt of Qualcomm failed as the U.S. government stepped in, and Qualcomm’s bid to secure NXP became embroiled in the ongoing trade war with China. Completed deals included Toshiba spinning off its NAND business into Toshiba Memory in June 2018 and Microchip’s May 2018 acquisition of Microsemi.
“2019 will be a very different market from the previous two years,” said Mr. Norwood. “Memory has already entered a downturn, there is the looming trade war between the U.S. and China, and mounting uncertainty about the global economy.”